Photoinitiators Market Recent Developments and Growth Analysis
Photoinitiators Market to Reach USD 6.01 Billion by 2034, Driven by UV Curing, Sustainable Coatings and Advanced Printing Technologies
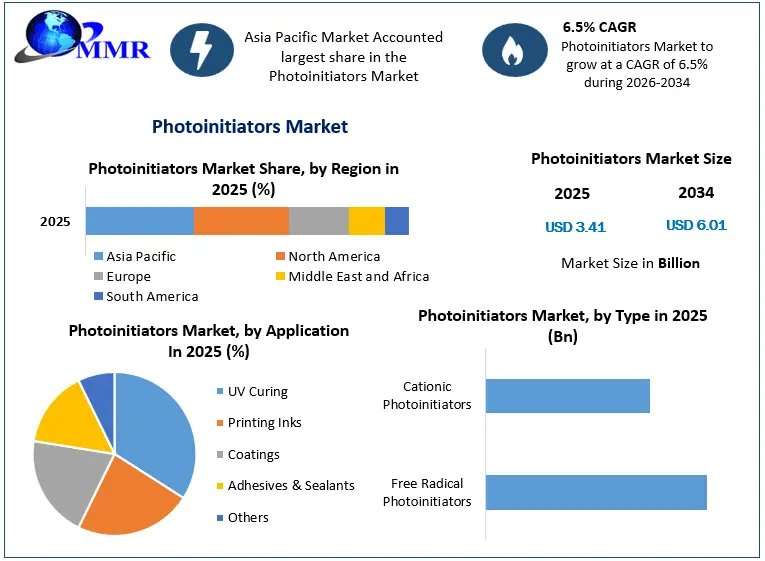
The Photoinitiators Market is entering a period of sustained expansion as demand increases for faster curing, energy-efficient manufacturing, low-emission coatings, high-performance printing inks, adhesives, electronics materials, and advanced 3D printing applications. According to Maximize Market Research, the global Photoinitiators Market was valued at USD 3.41 billion in 2025 and is projected to reach nearly USD 6.01 billion by 2034, expanding at a CAGR of 6.5% from 2026 to 2034.
Photoinitiators are essential chemical compounds that generate reactive species when exposed to UV or visible radiation, initiating polymerization and enabling rapid curing. Their ability to improve productivity, finishing quality, formulation flexibility, curing speed, storage stability, and application efficiency is supporting adoption across multiple industrial sectors.
Market Estimation, Growth Drivers and Opportunities
The market's growth is closely linked to the increasing adoption of UV-curable coatings and adhesives. UV curing enables rapid processing with reduced heat exposure and comparatively low VOC emissions, making it attractive for manufacturers seeking higher production efficiency and improved environmental performance. Growing applications in packaging, automotive, electronics, printing, industrial coatings, adhesives, and 3D printing are creating additional opportunities.
The transition toward ecological and energy-efficient products is another important market driver. Photoinitiator-based formulations can support faster production cycles while delivering attractive appearance, chemical resistance, corrosion protection, and durable finishes. Demand for advanced packaging and automotive coatings is also opening opportunities for specialty photoinitiator formulations.
However, volatility in raw-material prices remains a challenge for manufacturers. Differences in petroleum- and non-petroleum-based feedstock costs can affect production economics and product pricing. Regulatory requirements surrounding specific photoinitiator chemistries are also encouraging manufacturers to invest in safer, lower-migration, and more sustainable alternatives.
Request a Sample PDF of the Market Report : https://www.maximizemarketrese....arch.com/request-sam
United States Market Trends and Investment
The United States remains an important market for photoinitiators because of its established manufacturing base and strong adoption of UV-curable technologies across packaging, printing, electronics, healthcare, aerospace, automotive, and advanced manufacturing. During 2025, the industry continued moving toward high-performance and regulatory-conscious photoinitiator systems, particularly those compatible with UV-LED curing and applications requiring lower migration.
The growing use of digital printing and high-speed packaging production is strengthening demand for rapid-curing materials. At the same time, research and development in photopolymerization and 3D printing is expanding opportunities for specialized photoinitiators. In 2025, industry developments also included new research and intellectual-property activity around photocurable compositions for three-dimensional investment casting, demonstrating the expanding technology base for photoinitiator-enabled manufacturing.
Market Segmentation: Dominant Segments
By Type: The Free Radical Photoinitiators segment held the largest market share in 2025 and is expected to maintain its leading position throughout the forecast period. Their broad compatibility with monomers and resins, fast polymerization rates, cost-effectiveness, and ease of formulation make them widely used in coatings, inks, adhesives, and 3D printing.
By Application: UV Curing accounted for the largest market share in 2025. Its rapid processing, energy efficiency, low emissions, and ability to cure heat-sensitive substrates make it increasingly valuable across packaging, electronics, automotive, and 3D printing applications.
Competitive Analysis
The competitive landscape includes established specialty chemical companies and dedicated photoinitiator manufacturers. Among the leading companies identified in the market assessment are IGM Resins, BASF SE, Zhejiang Yangfan Materials Co., Ltd., Tianjin Jiuri New Materials Co., Ltd., and ADEKA Corporation.
IGM Resins continues to expand its energy-curing portfolio and technical capabilities. In 2025, the company introduced innovations including polymeric photoinitiators and water-based photoinitiator solutions. Its Omnirad, Esacure, Omnipol, and Omnicat portfolios address multiple UV and LED curing requirements.
 Tycka om
-

-

-

-

-

-

Kommentar
Dela med sig
Photoinitiators Market Recent Developments and Growth Analysis
Photoinitiators Market to Reach USD 6.01 Billion by 2034, Driven by UV Curing, Sustainable Coatings and Advanced Printing Technologies
The Photoinitiators Market is entering a period of sustained expansion as demand increases for faster curing, energy-efficient manufacturing, low-emission coatings, high-performance printing inks, adhesives, electronics materials, and advanced 3D printing applications. According to Maximize Market Research, the global Photoinitiators Market was valued at USD 3.41 billion in 2025 and is projected to reach nearly USD 6.01 billion by 2034, expanding at a CAGR of 6.5% from 2026 to 2034.
Photoinitiators are essential chemical compounds that generate reactive species when exposed to UV or visible radiation, initiating polymerization and enabling rapid curing. Their ability to improve productivity, finishing quality, formulation flexibility, curing speed, storage stability, and application efficiency is supporting adoption across multiple industrial sectors.
Market Estimation, Growth Drivers and Opportunities
The market's growth is closely linked to the increasing adoption of UV-curable coatings and adhesives. UV curing enables rapid processing with reduced heat exposure and comparatively low VOC emissions, making it attractive for manufacturers seeking higher production efficiency and improved environmental performance. Growing applications in packaging, automotive, electronics, printing, industrial coatings, adhesives, and 3D printing are creating additional opportunities.
The transition toward ecological and energy-efficient products is another important market driver. Photoinitiator-based formulations can support faster production cycles while delivering attractive appearance, chemical resistance, corrosion protection, and durable finishes. Demand for advanced packaging and automotive coatings is also opening opportunities for specialty photoinitiator formulations.
However, volatility in raw-material prices remains a challenge for manufacturers. Differences in petroleum- and non-petroleum-based feedstock costs can affect production economics and product pricing. Regulatory requirements surrounding specific photoinitiator chemistries are also encouraging manufacturers to invest in safer, lower-migration, and more sustainable alternatives.
Request a Sample PDF of the Market Report : https://www.maximizemarketrese....arch.com/request-sam
United States Market Trends and Investment
The United States remains an important market for photoinitiators because of its established manufacturing base and strong adoption of UV-curable technologies across packaging, printing, electronics, healthcare, aerospace, automotive, and advanced manufacturing. During 2025, the industry continued moving toward high-performance and regulatory-conscious photoinitiator systems, particularly those compatible with UV-LED curing and applications requiring lower migration.
The growing use of digital printing and high-speed packaging production is strengthening demand for rapid-curing materials. At the same time, research and development in photopolymerization and 3D printing is expanding opportunities for specialized photoinitiators. In 2025, industry developments also included new research and intellectual-property activity around photocurable compositions for three-dimensional investment casting, demonstrating the expanding technology base for photoinitiator-enabled manufacturing.
Market Segmentation: Dominant Segments
By Type: The Free Radical Photoinitiators segment held the largest market share in 2025 and is expected to maintain its leading position throughout the forecast period. Their broad compatibility with monomers and resins, fast polymerization rates, cost-effectiveness, and ease of formulation make them widely used in coatings, inks, adhesives, and 3D printing.
By Application: UV Curing accounted for the largest market share in 2025. Its rapid processing, energy efficiency, low emissions, and ability to cure heat-sensitive substrates make it increasingly valuable across packaging, electronics, automotive, and 3D printing applications.
Competitive Analysis
The competitive landscape includes established specialty chemical companies and dedicated photoinitiator manufacturers. Among the leading companies identified in the market assessment are IGM Resins, BASF SE, Zhejiang Yangfan Materials Co., Ltd., Tianjin Jiuri New Materials Co., Ltd., and ADEKA Corporation.
IGM Resins continues to expand its energy-curing portfolio and technical capabilities. In 2025, the company introduced innovations including polymeric photoinitiators and water-based photoinitiator solutions. Its Omnirad, Esacure, Omnipol, and Omnicat portfolios address multiple UV and LED curing requirements.